Get the policy
you paid for.
Denial reasons, claim deadlines, coverage law, carrier dossiers, and the storm record, for denied and underpaid property-insurance claims in Florida and South Carolina.

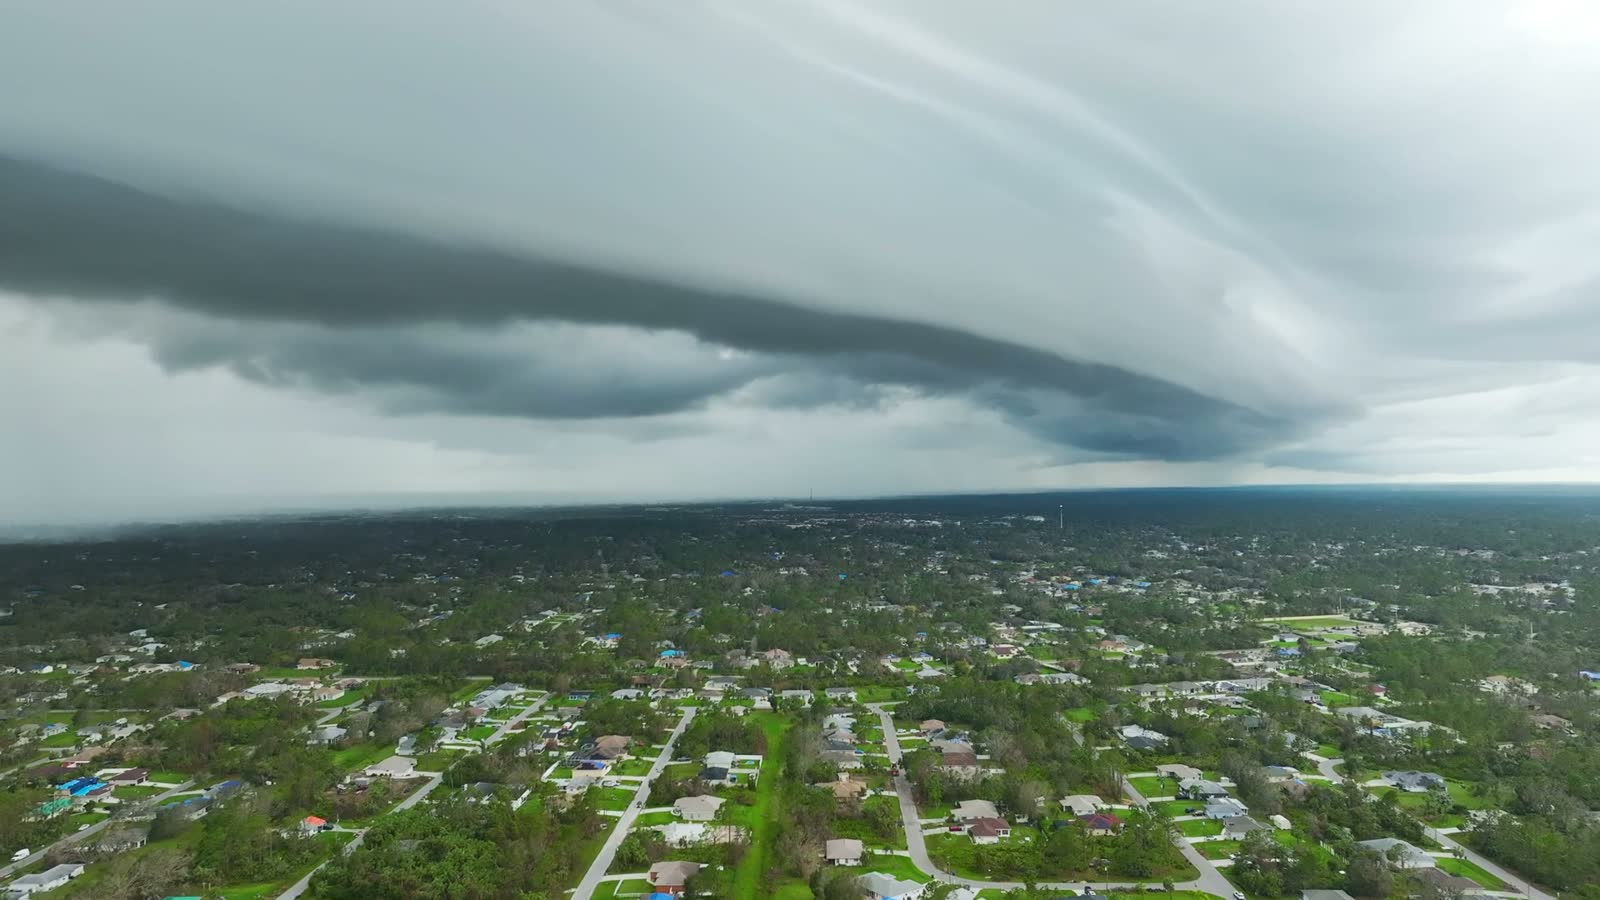
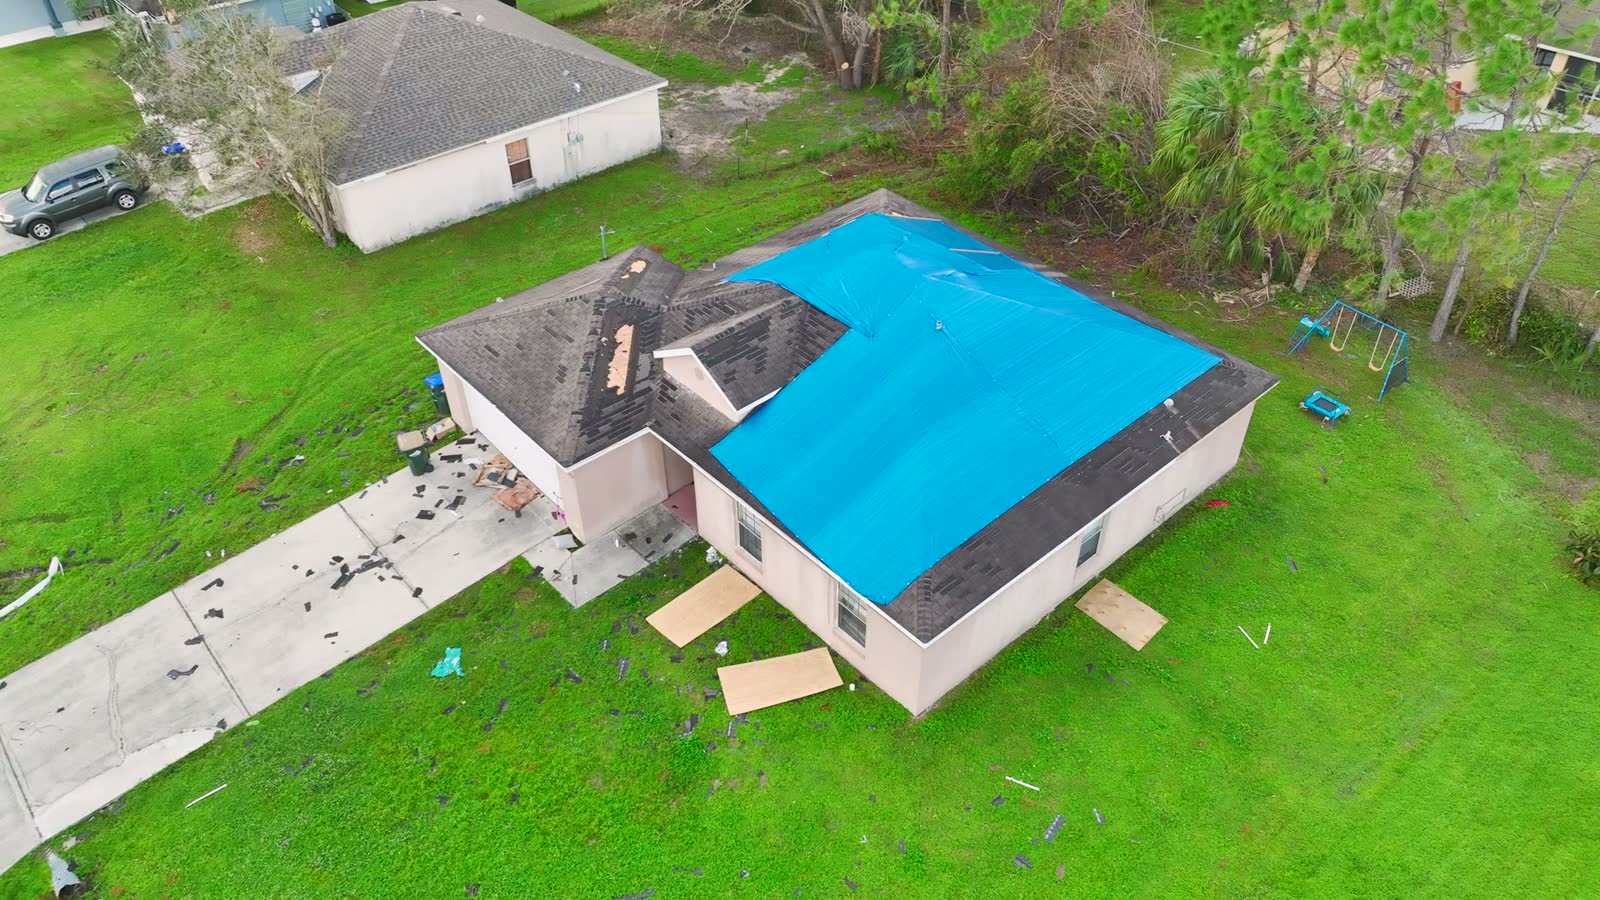
The complete playbook for fighting a denied or underpaid property-insurance claim.
A comprehensive property-insurance claim resource. Coverage law, a step-by-step claims playbook, the denial documents and the filing archive, storm dossiers, carrier dossiers, a public-adjuster directory, and contractor and expert guides.
Read your coverage, work the claim steps, and answer the denial with evidence. If the carrier will not pay what it owes, escalate: appraisal or mediation, a Civil Remedy Notice, or a lawyer.
Fill out the case-review form and licensed counsel reviews your claim and gets back to you. Suit is covered if the claim gets there. No fee unless you recover.
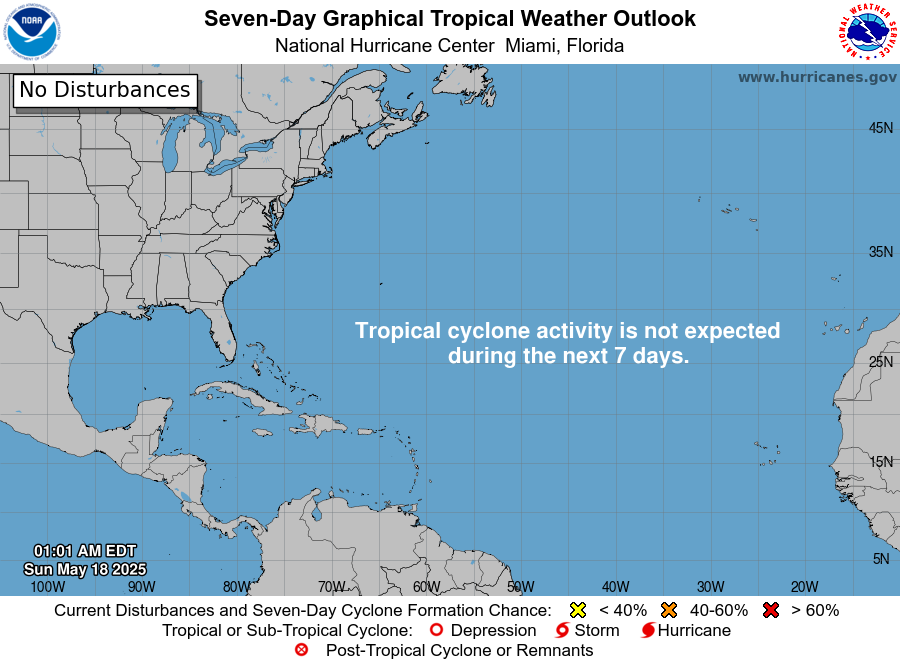
ATLANTIC BASIN · QUIET
HURRICANE SEASON · DAY 101 · 83 DAYS REMAINWhen do hurricanes actually hit?
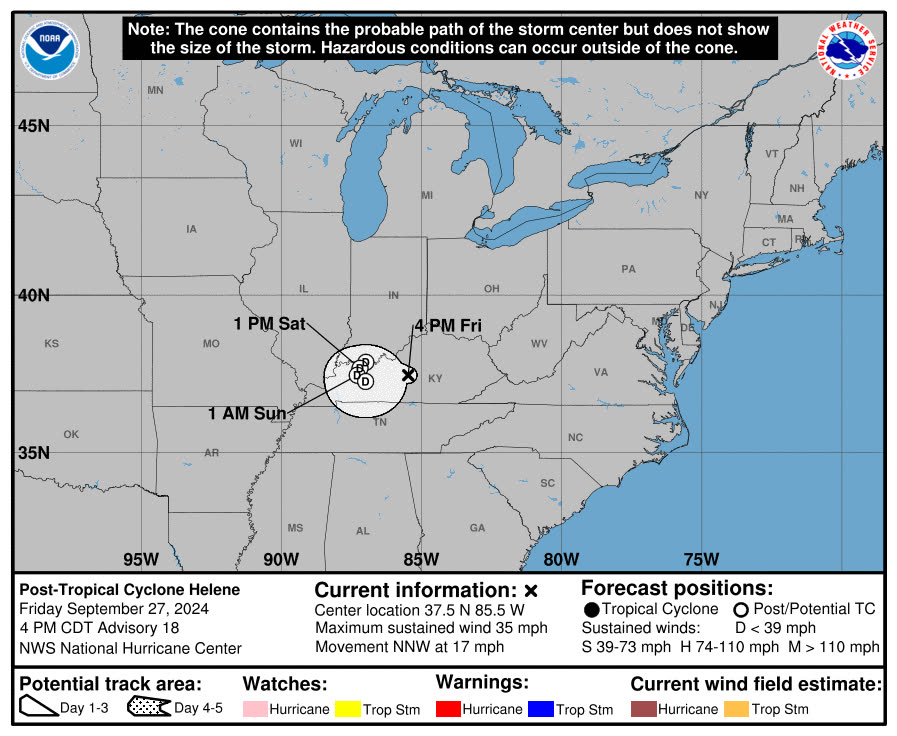
The season runs June 1 to November 30 and concentrates between late August and mid-October. The outlook page carries this year’s forecast, the storm names, and the pre-season list.
Hurricane climatology →What to do before the season
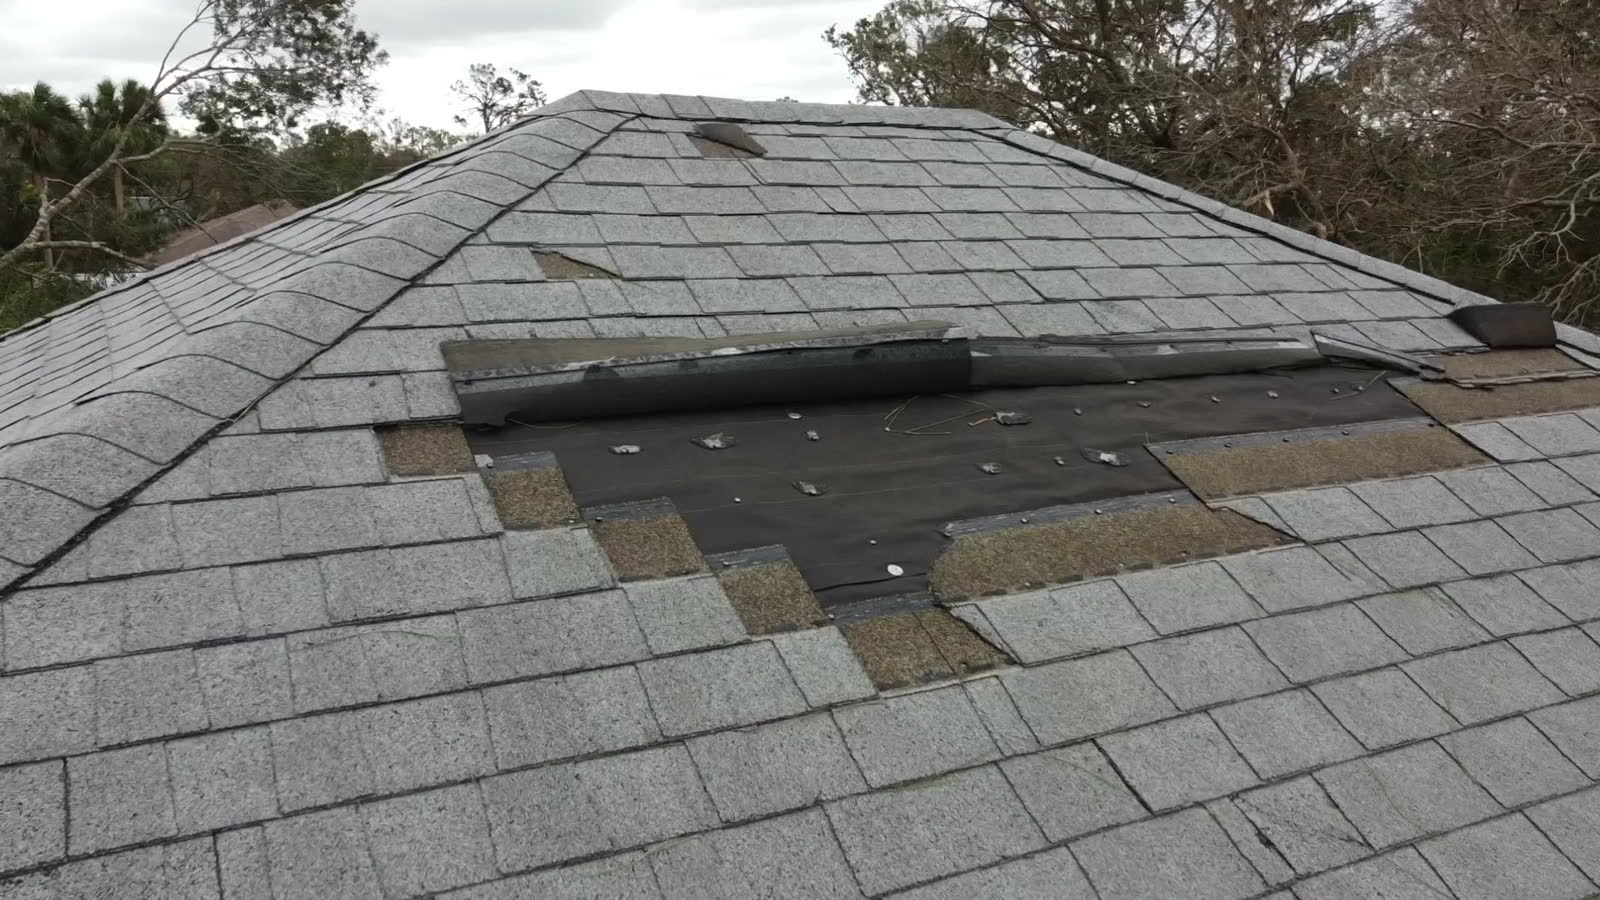
Photograph the roof, read the hurricane deductible on the declarations page, and keep a copy of the policy off-site. Do it before the storm, not after.
Pre-season checklist →What policyholders ask first
Each answered in a full guide.
Read the denials in the public file
165 documents in which a Florida or South Carolina insurer's own denial language appears, and 1,891 state filings over denied property claims. Searchable by insurer, by peril, and by the argument the carrier ran.
Every peril, every property type
Residential and commercial: fire, sinkhole and collapse, water and mold, business interruption, condo and HOA.
Built for the claim file
Know who you're dealing with
Public adjusters, carriers, and contractors.
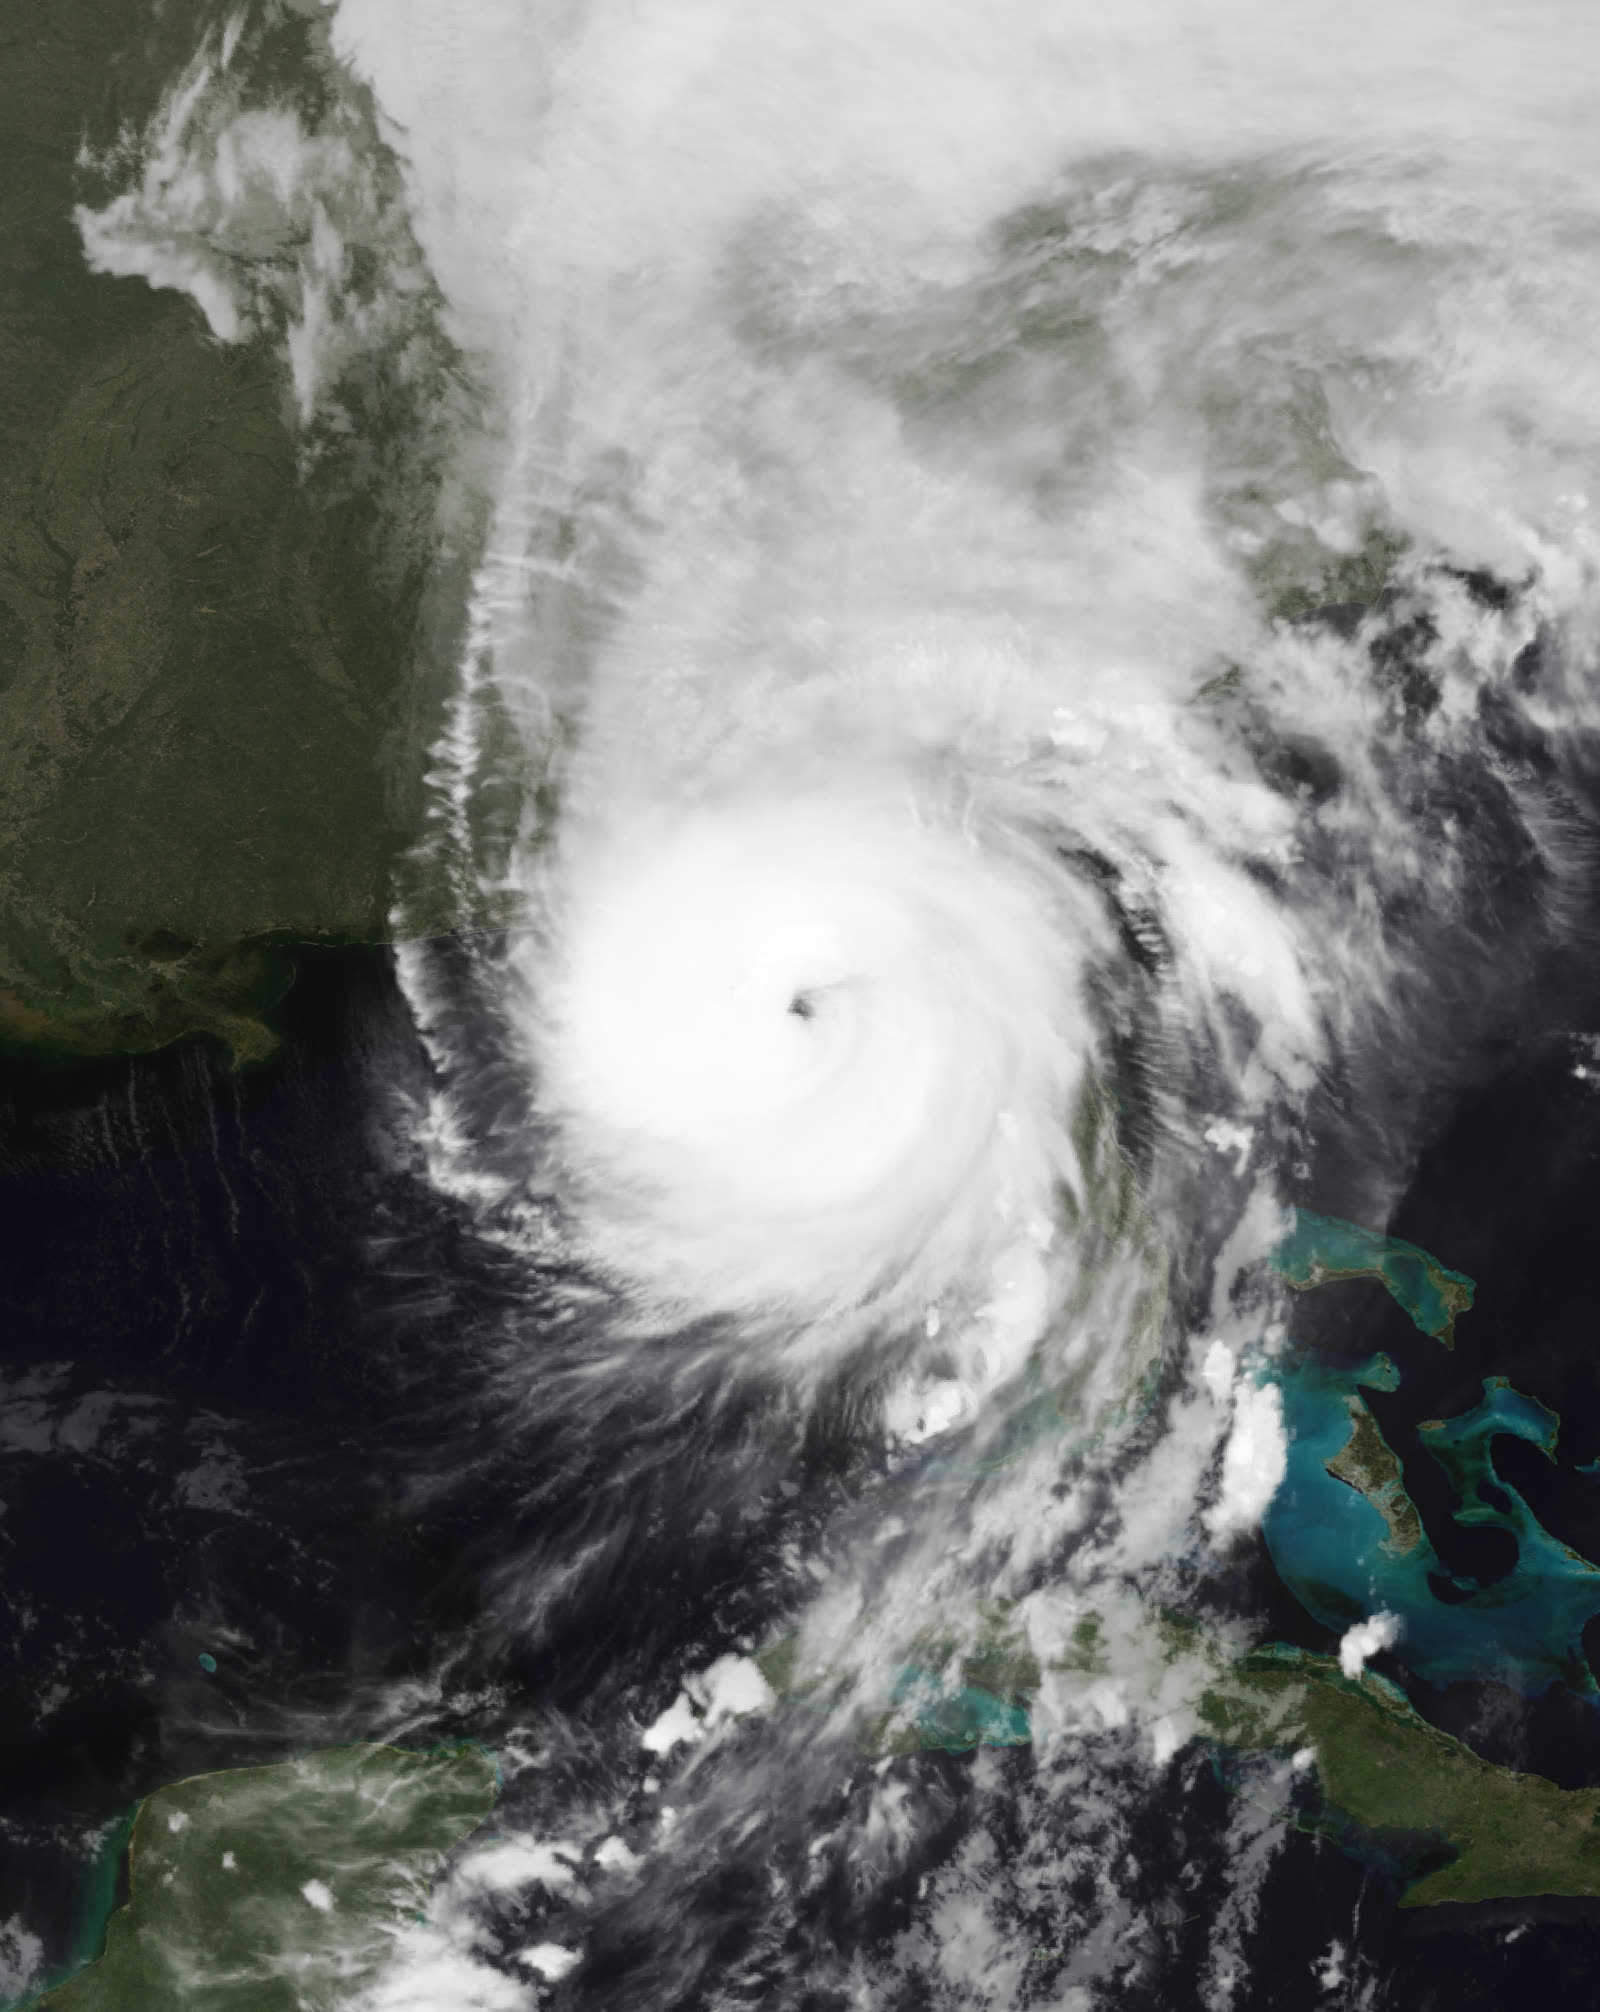
The storm dossiers
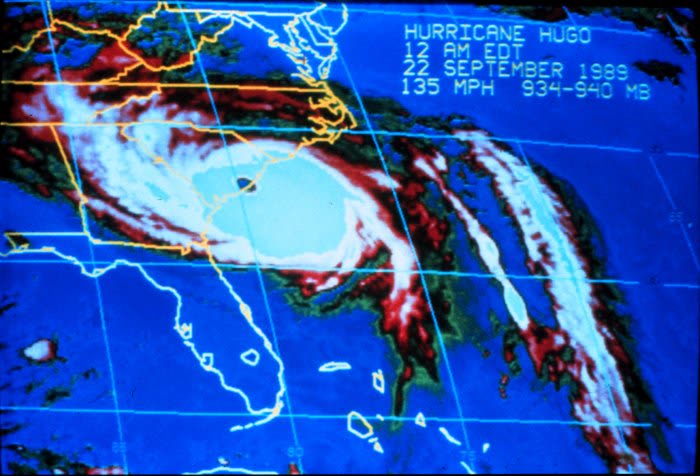
Where each storm hit, when, at what strength, and how the carriers handled the claims after it.
Long-form guides
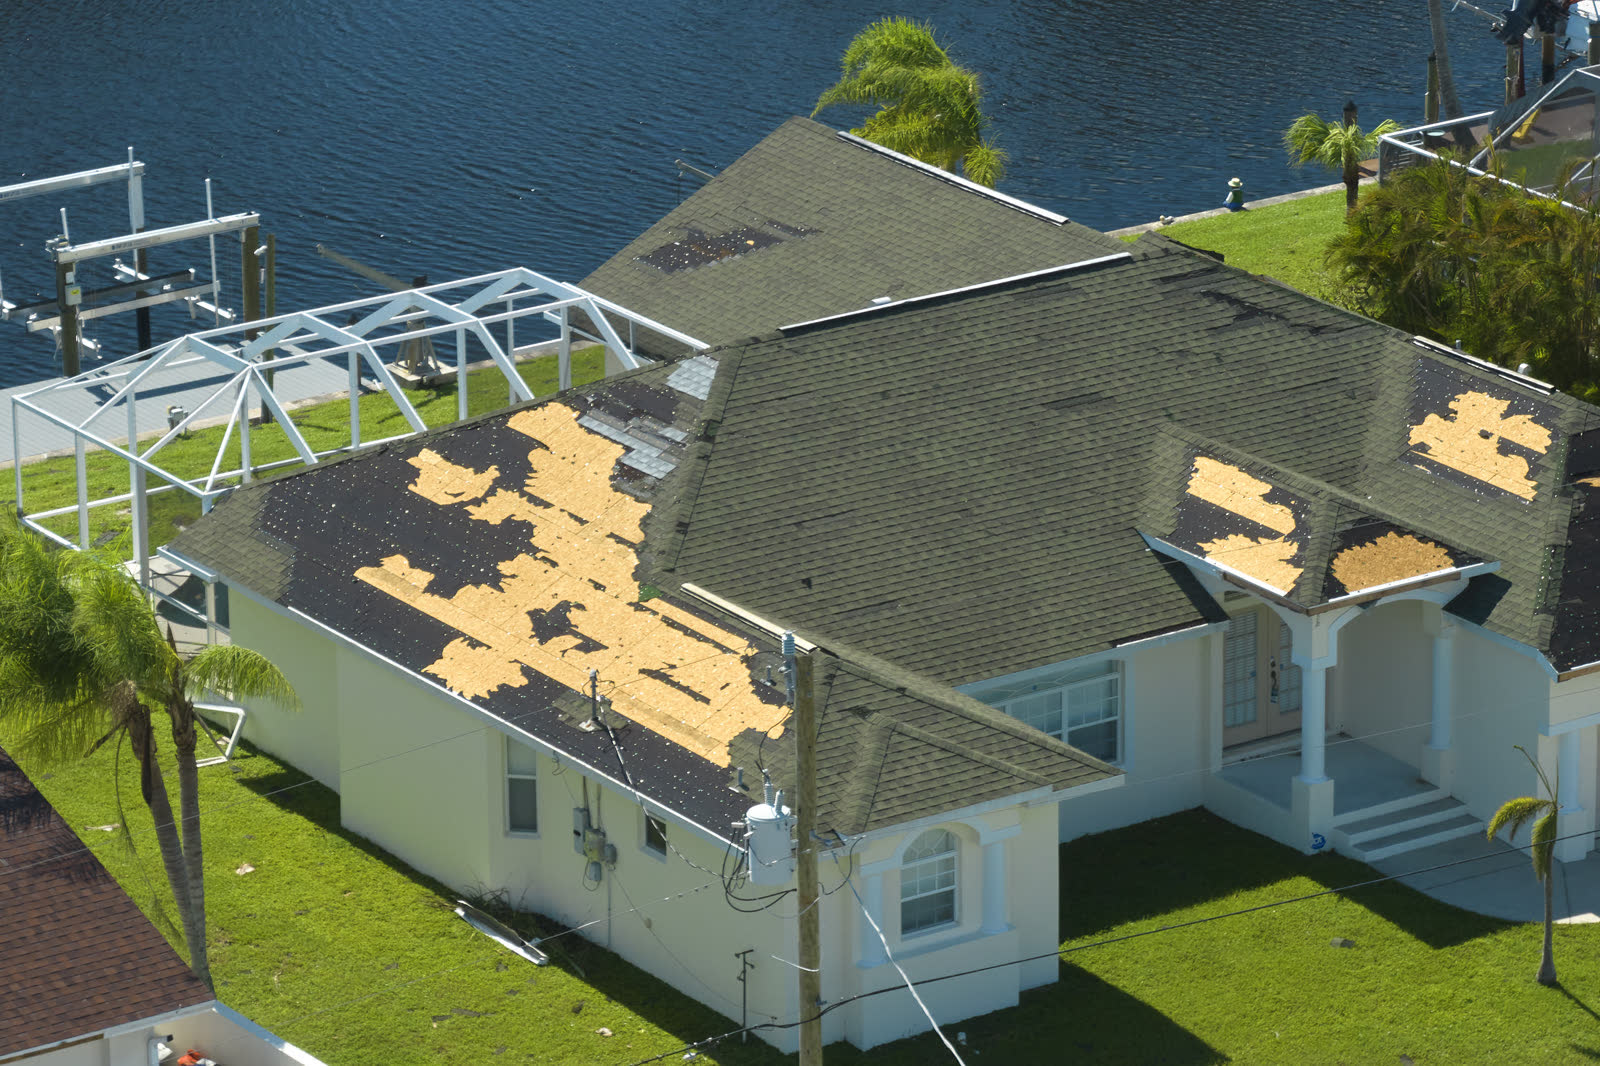
Roof claim denied: the complete response playbook
Wear-and-tear vs. wind damage, the engineer report, and four escalation paths.
Read →Hurricane deductibles, with real numbers
What the hurricane deductible is a percentage of, and what it costs on a real dwelling limit.
Read →Claim law changes in FL and SC
Statute changes, carrier conduct, and the storms behind the claims being fought now.
Read the feed →
 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP →Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.
Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.